
How much down payment do you need in Canada?
Canada's minimum down payment rules, how mortgage default insurance works below 20% down, and where your down payment can come from.
Key takeaways
- The minimum is 5% of the first $500,000, plus 10% of the portion above that.
- Homes priced at $1.5 million or more need at least 20% down.
- With less than 20% down, you'll pay for mortgage default insurance.
The minimum down payment
In Canada, the minimum down payment depends on the purchase price:
| Purchase price | Minimum down payment |
|---|---|
| Up to $500,000 | 5% of the price |
| $500,000 to $1,499,999 | 5% of the first $500,000, plus 10% of the rest |
| $1.5 million or more | 20% of the price |
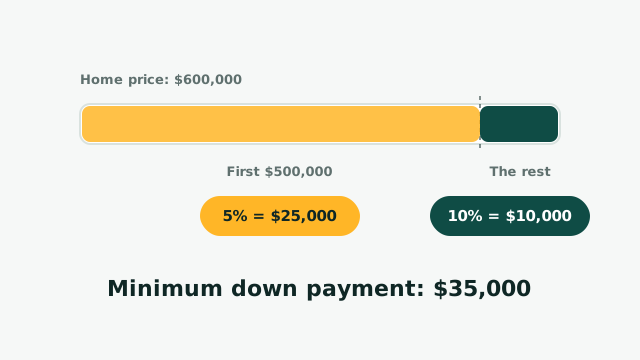
Example: on a $600,000 home, the minimum is 5% of $500,000 ($25,000) plus 10% of $100,000 ($10,000), for a total of $35,000.
Mortgage default insurance
If you put down less than 20%, your mortgage needs default insurance, from CMHC or a private insurer. It protects the lender, not you, but it's what makes lower down payments possible.
- The premium is a percentage of your mortgage, roughly 2.8% to 4%, and it's higher when your down payment is smaller.
- It's usually added to your mortgage, so you pay it over time.
- In some provinces, including Ontario, Quebec and Saskatchewan, provincial sales tax on the premium is due at closing.
Is 20% down better?
Putting down 20% or more avoids the insurance premium and lowers your mortgage. But waiting years to save 20% isn't always the right call, especially if prices rise in the meantime. A broker can compare both scenarios for you.
Where your down payment can come from
- Your savings and investments
- A First Home Savings Account (FHSA)
- The RRSP Home Buyers' Plan
- A gift from a close family member, usually with a signed gift letter
Lenders typically want to see where your down payment came from, often with 90 days of account statements. Keep large deposits documented.
This guide is general information, not financial advice. Rules and products change, and every situation is different. A licensed mortgage broker can tell you what applies to you.